Shein, Temu and AliExpress Lost Over a Third in Germany. The Rest of Online Retail Sped Up.
The e-commerce association bevh puts third-quarter German sales at Shein, Temu and AliExpress down 35.5% after the EU ended the €150 duty exemption, and its chief executive says domestic sellers could not benefit. Take the three platforms out of bevh's own figures and everyone else grew faster than in either earlier quarter this year, with clothing ahead of the market and, on bevh's earlier wording, marketplaces taking the gain.
Neritus Vale
German shoppers spent 35.5% less at Shein, Temu and AliExpress between July and September than a year earlier, in the first quarter since the EU ended its duty exemption for parcels under €150. The e-commerce association bevh, which measured the fall, says it pulled the whole market down and that domestic sellers could not benefit. Its own figures complicate that: take the three platforms out, and the rest of German online retail grew faster this summer than in either earlier quarter of 2026.
The release names two causes for the slowdown, and its body quote puts the shopper’s mood first. “Sharply rising energy prices and falling income expectations are making themselves felt in online buying behaviour,” said Alien Mulyk, bevh’s chief executive. The release sets the market’s nominal growth of 2.9% against September’s inflation rate of 3.3%. Its headline and standfirst lead with the platforms: Temu and Shein’s rapid growth “has stalled,” Mulyk said, so total sales are falling “without domestic providers being able to benefit from the weakness of Asian competitors.” TextilWirtschaft’s report by Anke Prokasky opened on the same poor mood and named fashion the pleasing exception.
Mulyk’s “falling” holds only after inflation, because total sales rose in money terms. September was the quarter’s highest-inflation month, and its 3.3% is a flash estimate; the final rate is due on 13 October. Destatis’s monthly rates for July to September average about 3.0%, and against that the market merely stalled.
Both the platform figures and the market total come from one weekly survey, run for bevh by BEYONDATA, which asks 40,000 people a year what they spend online; this release covers 1 July to 30 September. The platforms’ market share is their sales divided by the market total. Last year’s release put Asian suppliers at a 4.9% share of the same quarter, which squares with the fall.
Take the three platforms out, and everyone else’s online goods sales rose about 4.8%. The inputs are bevh’s: platform sales of €566m, about €878m a year earlier on the 35.5% fall, inside a market that grew from €17,960m to €18,473m. The platforms’ loss of about €311m accounts for the gap between that 4.8% and the headline 2.9%.
The same subtraction gives everyone else about 3.1% in the first quarter and an estimated 4.0% to 4.4% in the second. So the rest of the market grew fastest in the very quarter the headline grew slowest. The second-quarter figure is an estimate: bevh gave no platform sales for that quarter, only a share for Asian providers and growth of more than 20%.
Germany’s online slowdown this summer fits inside three websites.
Clothing, the category Shein was built on, hints at where the platforms’ customers went. In the second quarter Asian platforms accounted for “more than 16 per cent of all orders” in online fashion, bevh said in July, and their share of sales was still growing. This summer Shein, Temu and AliExpress shrank by more than a third, and clothing barely noticed: it grew 4.9%, faster than the market and slightly faster than in spring. The association does not publish the platforms’ sales by category, but if theirs fell anything like their total, clothing outside the platforms grew faster than 4.9%. In spring, with the platforms still growing, it grew more slowly than the segment did. On that reading, someone else sold the clothes.
The association’s seller-type lines say who, though for all goods rather than clothing alone. Online marketplaces grew 5.0%, the fastest of any seller type. Brands selling from their own sites and multichannel retailers grew no faster than in spring. Pure online shops, a line that also holds online pharmacies and shopping clubs, shrank 0.8%.
The release does not say which line holds the three platforms, but earlier bevh releases point to the marketplaces. Last October bevh wrote that “the strong growth of Asian platforms is also noticeable” in the success of the business models, then cited the marketplaces’ gain. In January it measured the three against “the entire provider segment of marketplaces.” If that is where they sit, the rest of the marketplace line grew about 9% this summer, nearly twice its pace in the first half, and almost all of everyone else’s gain went to marketplaces, none to pure online shops. If bevh books them under pure online shops instead, that line grows 6.6% without them, and the gain belongs to web shops.
The strongest objection is that the rest of the market was speeding up anyway. Everyone else’s growth had already climbed to an estimated 4.0% to 4.4% in the second quarter, before the duty applied. Inflation also rose between the second and third quarters, so in real terms everyone else grew at about the same pace in both. On that reading the platforms’ customers simply kept their money, and Mulyk’s sentence stands. For that reading to hold, the platforms’ slump should have dragged clothing below its spring pace and left the rest of the marketplace line where it was.
The marketplace line contradicts the objection under either measure of prices; clothing does so only in part. If the platforms sit in the marketplace line, the rest of it nearly doubled its pace, a jump far larger than the rise in inflation. Clothing did not slow in money terms and was flat to slightly slower after inflation, so the platforms’ slump did not pull it down, even as the sellers that had been taking share in it shrank. The mood did bite, but elsewhere: electronics and furniture fell, the purchases bevh says shoppers put off. Everyone else still grew faster in money terms through that drag, which fits the platforms’ lost sales going elsewhere.
The release leaves three things open: which seller line holds the platforms, how much of their sales were clothing, and whether “falling” means after inflation. Its table does not split “everyone else” by origin, so it shows that the rest of the market grew, not that domestic providers did. bevh publishes no margin of error for a survey of about 10,000 people a quarter, and the platforms are about 3% of spend, so the gap to the second-quarter estimate is small. The answers could change who won, though not the 4.8%, which needs only the platforms’ total and the market’s.
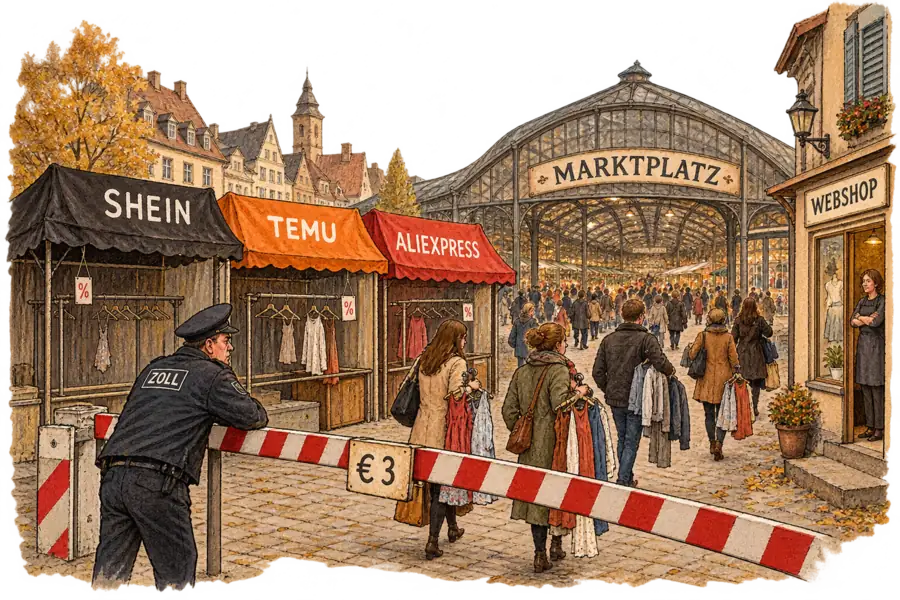
Only the €3 duty per customs category applied this summer; a €2 handling fee follows in November. In July, Mulyk expected the duty to have little impact, because suppliers were moving to European logistics. If marketplaces keep collecting what the platforms lose, the fourth quarter will show the same transfer. If European warehouses bring Temu’s and Shein’s prices back down, the flow can reverse.
Read as Mulyk reads it, the summer was something done to German retail: Brussels squeezed the platforms, and nobody here could profit. The table turns it into a choice. The shoppers the platforms lost kept buying clothes, and on bevh’s earlier wording their money went to marketplaces. If the November fee shakes more of them loose, a brand that waits for them at its own checkout has already chosen to let the marketplaces have them.
German-language quotations are translated by Rack & Reason.