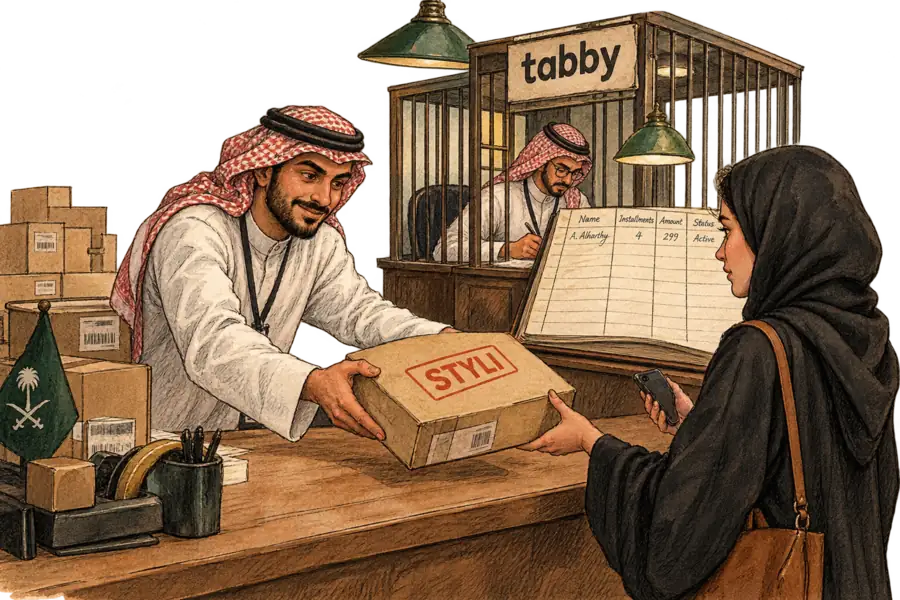
Tabby Underwrote Styli's Basket and Kept the Repayment File
Styli's instalment tie-up with Tabby funded the basket and relocated the record. Saudi rules oblige the lender, not the shop, to hold and update the shopper's credit file, which is the one dataset that says whether they come back.
Sir John Crabstone
Styli began splitting baskets into four interest-free payments in October 2021, naming Tabby its instalment provider and carrying the cashback facility Tabby had already built for its own customers. The Landmark-owned Saudi platform bought a conversion lift. Tabby opened a file, and has been writing in it since.
Gulf e-commerce growth now runs on that arrangement. Saudi shoppers bought SAR 36.6bn of goods on instalment plans in 2024, and the number of merchants offering them doubled to 121,000, Fintechnews Middle East reported from Fintech Saudi’s annual review. Nobody adds instalments out of generosity. They go in where the basket will not otherwise move, and the merchant pays for the privilege in more than a fee.
The trade reads these deals as conversion stories, and on that measure they work. Conversion is settled at the checkout. Everything that predicts the next order happens afterwards, on the lender’s side of the arrangement. Retailers audit the first number. They rarely see the second, and by the time they ask, the habit has already formed.
Saudi rules then made the record compulsory. Article 19 of the central bank’s buy-now-pay-later rules, issued in December 2023, obliges the provider to verify each consumer’s credit record before lending. It must also register that consumer’s credit information with a licensed bureau and keep it current “throughout the period of dealing with the consumer”. No equivalent duty falls on the shop, and no equivalent right: Articles 17 and 29 of the same rulebook bind the lender to confidentiality, so the file cannot even be handed back on request.
Five years of this produces a lender that knows the retailer’s customers better than the retailer does. Tabby reached 15 million users, 40,000 brands and annualised volume above $10bn by February 2025. Customers once used it only for e-commerce or point-of-sale spending, Hosam Arab said then; in the UAE especially, “they see Tabby as a tool to manage all their spending”. Styli knows what it sold. The rest sits with Tabby: what the shopper paid, missed, returned and bought next at every other merchant on the network.
The pitch to merchants is candid about the trade. “Receive the full amount in days. Zero risk to your business.” The risk moves across, and so does everything learned by carrying it.
The retailer is paid once; the lender is paid four times, and learns something on each occasion.
Landmark built Styli to reach a Saudi customer its group storefronts could not, a split we traced last month. On merchandising the logic held. On credit it inverts: the group acquires the shopper, and the evidence of whether they come back accrues elsewhere, compounding with every instalment plan Styli signs.
Tabby has hired HSBC, JPMorgan and Morgan Stanley for a listing on the Saudi Exchange, flagged in May 2025 for within twelve to eighteen months. It will take a credit book to market, priced on data no prospectus will need to name a merchant to justify. The asset is the record underneath it, assembled one basket at a time, at tills Tabby never owned. Styli sold the goods. Tabby will sell the file.